Same rules, different realities: Australia's first ASRS assurance cycle and what it taught us
- Post Date
- 03 September 2026
- Read Time
- 4 minutes
If you have clicked on this article, you have either just survived your first ASRS reporting and assurance cycle or you are nervously watching it approach. As Group 1 reporters completed their inaugural climate reporting, one thing became apparent: while the requirements are the same, assurance experiences are extremely varied. Yet beneath those differences sat a number of common themes, challenges and questions that surfaced repeatedly across assurance reviews.
In this article, we will share the lessons we learned from supporting over 30 companies through their first year of reporting, unpack the areas that are facing the most scrutiny, and provide practical guidance on what to do differently next year.
Our findings
So, what were the big sticking points for assurance providers? Five key themes consistently emerged as critical:
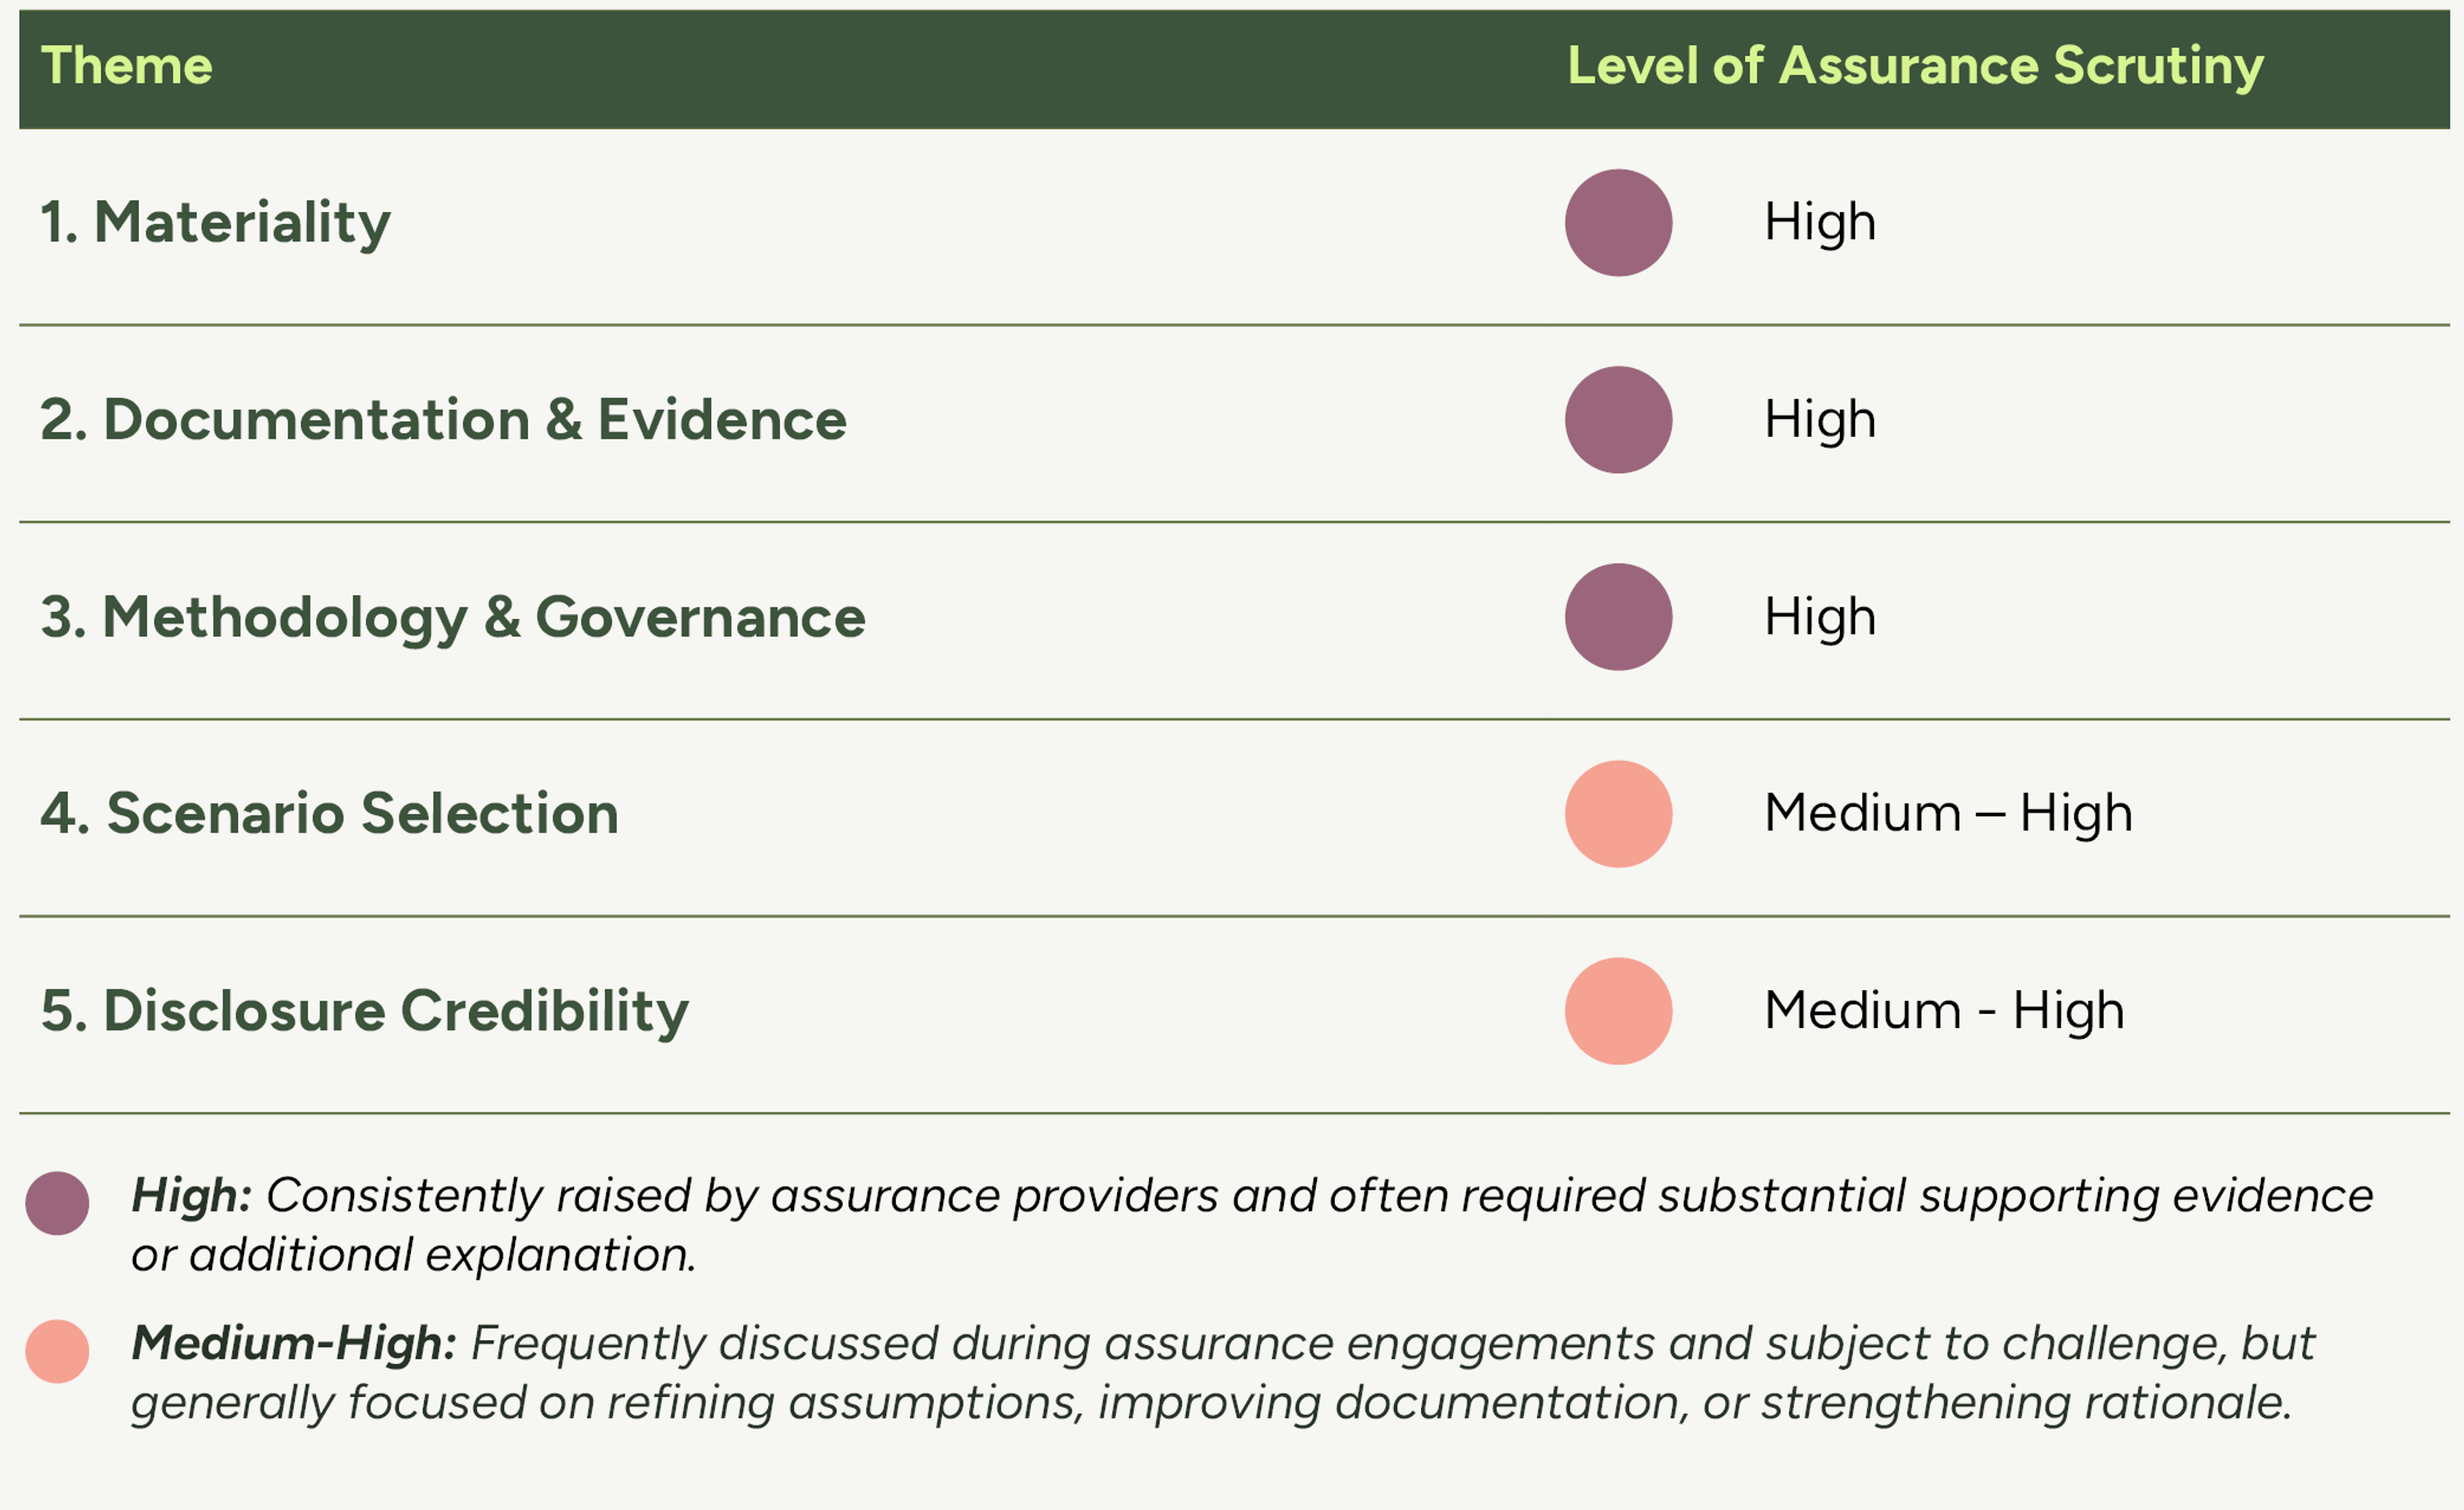
1. Materiality judgements must be transparent
Lesson: Materiality must be defensible, how did you decide what matters? who made that decision, on what basis and with what context?
2. Without documentation, it cannot be assured
Lesson: Evidence is crucial. If it’s not documented somewhere, in meeting minutes, reports, memos then in the eyes of the assurance provider, it didn't happen.
3. Methodology and governance are as important as the outcome
Lesson: Process matters (more often than not, more than the outcome). Assurers want to see the methodology to illustrate decisions have not been made arbitrarily and, not just the result, they want to be confident that it could be emulated, and that points 1 & 2 above support that.
4. Scenario analysis needs to connect to business impacts and decision making
Lesson: Scenarios need a story. Assumptions relating to scenarios need to connect to the business, simply reflecting the science, although robust, might not be the most practical position for the business commercially.
5. Excuses will no longer cut it
Lesson: Being new to ASRS reporting is no longer a defense. Many companies leant on time pressure, uncertainty and evolving approaches to justify missing or partial disclosures. Auditors showed limited tolerance of this in year 1 and this tolerance is only expected to reduce from year 2 onwards.
Our observations are based on over 30 ASRS engagements, including direct interactions with assurance providers and advisory support to reporting entities throughout the reporting and assurance process. These experiences have provided valuable insight into the area’s most frequently challenged during first-year assurance reviews.
What you should be ready for next time around?
The first round of assurance made one thing clear for us, that the biggest challenges were in evidencing disclosures rather than writing them.
FOR GROUP 1:
If you have already completed your first ASRS reporting and assurance cycle, the message is clear: the bar will continue to rise. The areas that attracted challenge in your first cycle are likely to receive even greater attention in future years, with expectations around documentation, governance and judgement becoming more rigorous.
The lessons should be viewed as a guide to where processes, controls and evidence trails can be strengthened ahead of the next reporting cycle.
FOR GROUP 2 & 3:
Group 1’s experience offers a valuable opportunity to prepare early and avoid common pitfalls.
Three key lessons:
- Call your assurance provider now and get ahead of the conversation by discussing key reporting decisions early. Ask questions, test their position, and clarify your intentions on certain reporting considerations. Once an assurance provider has settled on a particular view or approach, it can be difficult to revisit later, and can create unnecessary rework when reporting begins. (climate scenario decisions are a good example of this).
- Document, document, document. Don't wait until the assurers ask to start collecting data and filing evidence. Putting reporting frameworks, controls, and documentation processes in place now will save significant time and effort later.
- Use proportionality and uncertainty disclosures sparingly. While they can be valuable in the right circumstances, they are not a shortcut. If you rely on them, be prepared to explain your rationale and demonstrate how you arrived at your conclusions. (learn more via this article)
Ultimately, you need to treat assurance readiness as a year-round, incremental activity rather than a year-end exercise.
For more information on how SLR can support your ASRS process, get in touch with our team today.
Contact us